DSCR LOANS FOR REAL ESTATE INVESTORS

Investor financing, built around the property.

DSCR financing may allow real estate investors to qualify primarily using the property's rental income instead of traditional personal income documentation.

Purchase, refinance or access eligible equity while keeping the property, cash flow and investment objective at the center of the financing decision.

Already have a deal? Start with the property and the numbers you know. A scenario review is not a loan application.

DEAL SNAPSHOT What drives the conversation
Investor financing
PROPERTY Rental real estate
RENTAL INCOME Property cash flow
HOUSING OBLIGATION Property debt
RENT Income
÷
PAYMENT Obligation
=
RESULT DSCR
THEN LOOK BEYOND THE RATIO Leverage · Credit · Reserves · Structure · Strategy
01
Purchase

Finance an investment property.

02
Refinance

Restructure existing property debt.

03
Cash-Out

Explore access to eligible equity.

HOW DSCR WORKS

Qualify from the property’s cash flow. Then evaluate the whole deal.

DSCR stands for Debt Service Coverage Ratio. It compares the property’s qualifying rental income with the housing obligation used by the loan program.

THE BASIC CALCULATION
QUALIFYING RENTAL INCOME Property income
÷
QUALIFYING HOUSING OBLIGATION Property debt
=
RESULT DSCR

The exact income and expense treatment used for qualification can vary by lender and program.

WHAT THAT REALLY TELLS US

Does the property’s qualifying income support its required housing payment?

That ratio is the starting point. It does not determine the full loan structure, leverage, pricing, reserves or whether the financing supports your investment strategy.

01
ESTABLISH THE RENT Determine the qualifying rental income.

Depending on the property and program, the analysis may consider current rent, market rent or other acceptable documentation.

02
ESTABLISH THE OBLIGATION Determine the housing expense used in the calculation.

Principal, interest, property taxes, insurance, association dues and other applicable expenses may affect the ratio.

03
REVIEW THE REST Then look at the actual financing structure.

Loan-to-value, credit, reserves, property type, loan purpose, pricing and prepayment terms can all shape the final option.

SIMPLE EXAMPLE

Here’s what the math looks like.

MONTHLY RENT $2,500
÷
HOUSING OBLIGATION $2,000
=
DSCR 1.25
THE TAKEAWAY

A good ratio can help the property qualify. It does not automatically make the financing a good investment decision.

The next step is looking at leverage, pricing, structure and the investor’s objective together.

WHERE DSCR FINANCING MAY FIT

One financing approach. Three very different investor decisions.

Buying a rental property, replacing existing debt and accessing property equity each start with a different objective. The financing should be reviewed in that context.

01
ACQUIRE

Purchase

Finance the next investment property.

For a purchase, the conversation starts with the property, expected rental income, purchase price, requested loan amount and the cash you plan to bring to closing.

LOOK AT
  • Purchase price
  • Expected rent
  • Down payment
  • Target payment
02
RESTRUCTURE

Refinance

Reevaluate the debt already on the property.

A refinance may be worth reviewing when you are replacing short-term financing, changing the loan structure or comparing existing debt with another long-term option.

LOOK AT
  • Current balance
  • Existing payment
  • Proposed terms
  • Expected hold period
03
ACCESS EQUITY

Cash-Out

Explore whether property equity can help fund the next move.

A cash-out refinance may allow an investor to access eligible equity for another acquisition, property improvements, additional reserves or another investment objective.

LOOK AT
  • Current value
  • Existing debt
  • Cash needed
  • Use of funds
START HERE

Start with what you want the financing to accomplish.

Then evaluate the property, cash flow, leverage and loan structure against that objective.

Review My Scenario
BEYOND THE RATIO

The ratio opens the door. The structure shapes the deal.

A DSCR calculation can help determine whether the property supports the financing, but it is only one part of the scenario. The rest of the loan still matters.

THE FINANCING PICTURE

A workable DSCR doesn't tell you everything you need to know.

Investors still need to understand how leverage, pricing, liquidity, loan terms and the investment objective fit together.

THE BETTER QUESTION Does the financing support what you're trying to accomplish with the property?
01
LEVERAGE

How much financing are you placing against the property?

Purchase price, estimated value, requested loan amount and available equity can all affect the financing structure.

02
INVESTOR PROFILE

What does the borrower profile support?

Credit profile, reserves, liquidity, ownership structure and other program requirements can affect eligibility, leverage and pricing.

03
LOAN STRUCTURE

What are you receiving in exchange for the payment and cost?

Rate, points, amortization, interest-only options, loan term and other provisions can change the economics of the financing.

04
FLEXIBILITY

How does the loan fit the expected hold strategy?

Prepayment provisions, expected ownership period and future plans for the property can matter when comparing available options.

05
INVESTMENT OBJECTIVE

What does the financing need to help accomplish next?

Cash flow, equity access, liquidity, acquisition speed and capital for the next property can point toward different financing priorities.

LOOK AT THE WHOLE DEAL

Three questions worth separating.

01 Can it qualify?

Review the applicable loan requirements.

02 How should it be structured?

Compare leverage, payment, cost and terms.

03 Does it support the investment?

Put the financing back into the context of the objective.

+
THE ADVANTAGE More than a ratio. More context around the financing decision.
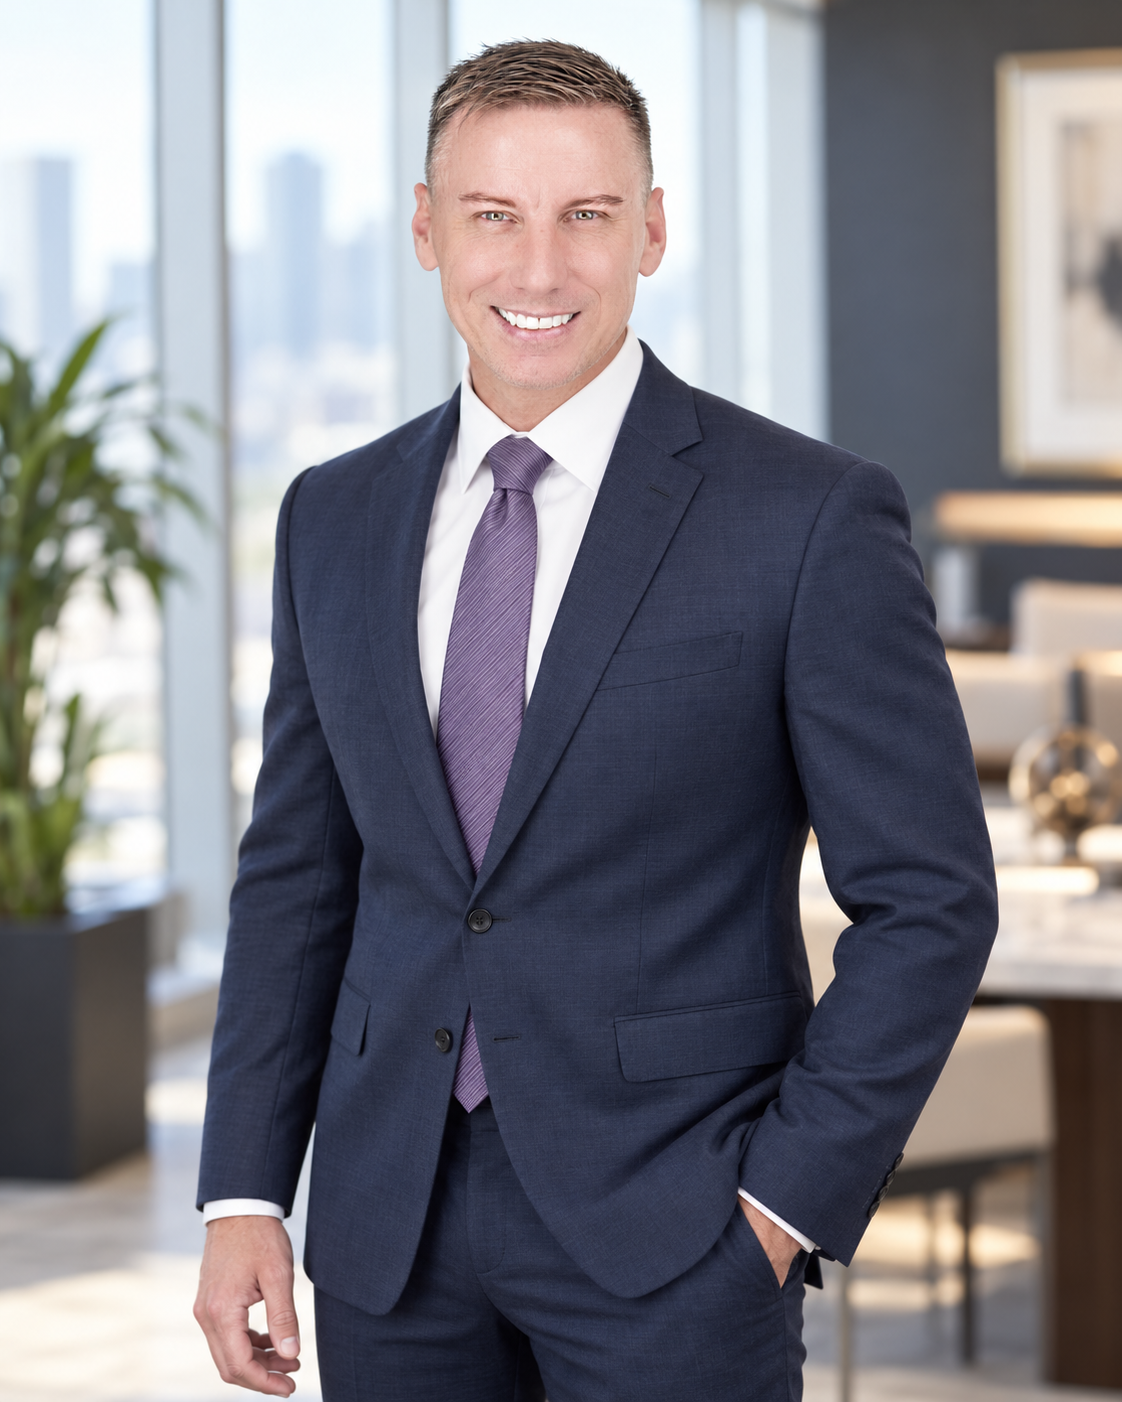
Victor Emmel
30+ YEARS IN
MORTGAGE LENDING

Experience across origination, processing, operations, technology and mortgage strategy.

Victor Emmel Mortgage Loan Advisor · NMLS #133605
WHY DSCR ADVANTAGE

Start with the deal. Not with the loan product.

Investment-property financing works better when the conversation begins with the property, the numbers and what you are trying to accomplish—not with a rate sheet or a predetermined loan structure.

MY APPROACH

I want to understand the scenario before recommending a direction. That means looking at the property cash flow, requested leverage, financing terms and investment objective together.

01
DEAL FIRST

Review the property before talking products.

The property, rent, value, current debt and financing objective give us the context needed to have a useful conversation.

02
COMPARE THE STRUCTURE

Look beyond the interest rate.

Payment, leverage, points, loan term, amortization, prepayment provisions and flexibility can all matter when comparing options.

03
EXPLAIN THE TRADEOFFS

Better financing decisions usually involve choices.

More leverage may change pricing. Lower upfront cost may affect the rate. Greater flexibility may come with different terms. Those tradeoffs should be clear before you decide.

04
KEEP THE INVESTMENT IN VIEW

The financing should support what comes next.

Whether your priority is cash flow, access to equity, another acquisition or long-term flexibility, the loan should be evaluated in that context.

+
THE DSCR ADVANTAGE

More context before you make the financing decision.

Review the scenario first. Understand the structure and tradeoffs. Then decide whether it makes sense to move forward.

Review My Scenario
INVESTOR RESOURCES

Understand the loan. Then run the deal.

Use these tools and guides to understand how DSCR financing works, explore the numbers and decide when you're ready for a scenario review.

?
NOT SURE WHERE TO START?

If you already have a property, skip the research and send the scenario.

You do not need every number finalized. Estimates are enough to begin identifying the questions that matter.

DSCR LOAN FAQ

A few questions investors usually ask first.

DSCR programs vary by lender and scenario, but these answers cover the basic ideas worth understanding before reviewing a property.

Learn More About DSCR Loans
01 What is a DSCR loan?

A DSCR loan is an investment-property financing option that generally places greater emphasis on the property's qualifying rental income and housing obligation than on traditional personal income documentation.

02 Do I need tax returns or pay stubs to qualify?

Many DSCR programs are designed to evaluate the property primarily through its rental income rather than using the traditional personal-income documentation required by many conventional loans. Documentation requirements still vary by lender and program.

03 Can DSCR financing be used for purchases and refinances?

DSCR programs may be available for investment-property purchases, rate-and-term refinances and cash-out refinances. Available leverage, pricing and requirements depend on the property and specific loan program.

04 What if the property's DSCR is below 1.00?

A lower DSCR does not automatically mean every financing option is unavailable. Some programs may permit lower ratios or use different structures, but leverage, pricing and other requirements can change. This is a good scenario to review before making assumptions.

05 Can I close a DSCR loan in an LLC or other entity?

Many DSCR programs permit eligible investment properties to be vested in an LLC or other approved entity. The exact entity, guarantor and documentation requirements depend on the program.

06 What should I send you for a scenario review?

Start with the property, estimated value or purchase price, expected rent, requested loan amount and what you are trying to accomplish. Estimates are fine for an initial review.

Review My DSCR Scenario →
HAVE A DEAL IN MIND?

Start with the property. We’ll work through the financing from there.

Send the numbers you already have—property details, estimated rent, value or purchase price, requested loan amount and what you are trying to accomplish.

You do not need a perfect scenario or every document ready. The first step is simply understanding the deal well enough to identify the financing options and tradeoffs worth reviewing.

A scenario review is not a loan application, approval, rate lock or commitment to lend.

START WITH WHAT YOU KNOW A few numbers are enough to begin.
01
Property

Address, property type and current status.

02
Income

Current or expected monthly rental income.

03
Financing

Purchase price, value, balance or requested loan amount.

04
Objective

Purchase, refinance, equity access or another strategy.

THEN WE CAN REVIEW Qualification · Leverage · Structure · Tradeoffs
PREFER TO TALK FIRST? Call, text or email Victor directly.
CALL OR TEXT 801-819-5901 EMAIL [email protected]
Victor Emmel Mortgage Loan Advisor · NMLS #133605
Coast2Coast Mortgage, LLC NMLS #376205 · Equal Housing Lender
Licensed In Utah · California · Idaho · Oregon · Washington · Texas